Are commodities the place to hide?
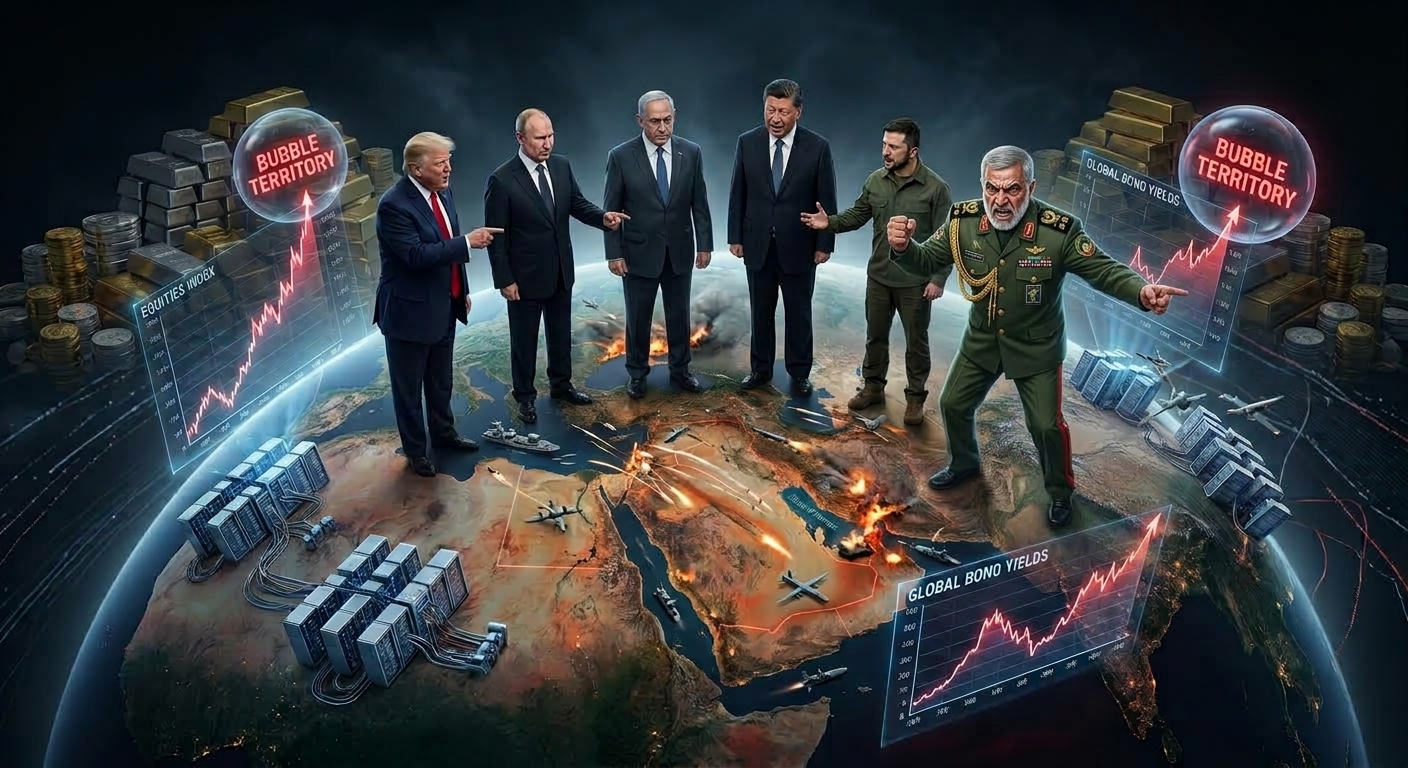
There is a particular kind of quiet that settles over a portfolio when everything is going wrong at once. Not a crash; a crash is at least legible. This is something slower: an index near its highs, a bond market that won’t behave, an oil price that moves on shipping lanes rather than barrels, and a nagging sense that the assets which have carried returns for three years are the same ones that would break hardest.
That is roughly where investors find themselves in September 2026. Brent has spent the last month oscillating around US$105 a barrel as the Strait of Hormuz stays semi-functional and diplomacy stops and starts. Chicago wheat sits near two-year highs with Ukraine’s deep-water ports effectively shut and Black Sea shipping under attack.
Washington is running a 50% tariff wall against Canada, which retaliated dollar-for-dollar on 8 September, while separate Section 301 duties reach across sixty economies. US federal interest payments have crossed a trillion dollars annually and now exceed the defence budget, with the deficit running about 10% ahead of last year. Bond yields are near multi-year highs (Australia’s ten-year recently hit levels last seen in 2011) and markets are pricing a real chance of the Fed hiking into all of this.
And sitting on top of that stack is the largest capital-spending boom in corporate history, with something over US$2.5 trillion of AI investment expected globally this year, roughly half of it poured into data centres, funded by a handful of companies that now make up more than a third of the S&P 500.
So the question we’re asking: are commodities the place to hide?
Four forces, not one
It helps to separate what is actually pushing raw materials around, because the drivers have very different half-lives.
Conflict premium. Hormuz and the Black Sea are supply-side shocks. They lift crude, gas, fertiliser and grain quickly, and they can unwind just as quickly on a ceasefire headline. This is the noisiest component and the one most likely to reverse.
Trade fragmentation. Tariffs, export controls and critical-minerals agreements are re-routing physical flows and adding cost at every border crossing. This is slower-moving, more durable, and generally inflationary at the margin.
Fiscal arithmetic. This is the one that matters most for long-horizon investors. When interest costs compound faster than revenue, the pressure eventually lands on the currency. The so-called debasement trade (selling sovereign bonds and the currencies they’re denominated in) is precisely what drove gold’s extraordinary 2025 and the central bank buying that continues underneath it.
Electrification and compute. AI data centres, grid rebuilds, EVs and rearmament all consume metal. Copper is the clearest example: the market is heading into deficit, Chilean output recently hit a nine-year low, and the average copper mine takes roughly 17 years from discovery to production. Approvals signed today don’t produce metal until the 2040s.
Only the last two are structural. Any commodities thesis that rests mainly on the first is a trade, not an allocation.
Are commodities actually a safe haven?
Here the honest answer is no, at least not in the way most people mean it.
A safe haven is something that holds value when everything else falls. Commodities don’t do that. They are volatile, cyclical, produce no cash flow, and they fall hard whenever growth disappoints. What they do (and it is genuinely valuable) is pay off in the specific scenarios where a conventional 60/40 portfolio suffers most: supply shocks, sustained inflation, currency debasement. That’s not insurance against volatility. It’s insurance against a particular type of loss.
2026 has illustrated both sides in one calendar year. Broad commodities, measured by the Bloomberg Commodity Index, posted one of their strongest first halves on record, up about 14% through June and comfortably ahead of global equities. But inside that number, the second quarter was an 8% drawdown as Hormuz tensions eased. Gold set a record above US$5,100 in late January and then spent months grinding back toward the low $4,000s before settling near $4,350: a round trip of roughly 25% for the asset everyone calls “safe.” Precious metals actually fell 7.6% over the first half while industrial metals rose 6.6%.
Anyone who bought gold in late January as protection has spent 2026 being protected in a way that felt a lot like losing money.
The lesson isn’t that the hedge failed. It’s that commodity hedges pay off on their own schedule, not yours, and sizing has to reflect that.
Is this a commodity supercycle?
The bull case is not silly. Structural deficits in copper. A decade of underinvestment in mine supply and upstream energy. Demand from three simultaneous build-outs (grid, defence, data centre) that didn’t exist in the last cycle. A fiscal backdrop across the entire developed world that argues for hard assets over paper claims. The World Bank has flagged several base metals reaching all-time highs this year, and long-dated bank forecasts for copper cluster well above spot.
The bear case deserves equal airtime, and rarely gets it.
High prices cure high prices. The IEA has already cut its outlook sharply, projecting global oil demand to contract by 2.5 million barrels a day in 2026 (the steepest annual decline since the pandemic) precisely because prices are high. That is demand destruction happening in real time, and it caps the energy leg of the thesis. China’s construction and services activity remains weak. Substitution and thrifting erode metal intensity over time. And if the AI capex cycle slows, a meaningful chunk of the incremental copper and power demand story slows with it, which means the “commodities hedge the AI bubble” argument is weaker than it sounds, since both trades lean on the same spending.
The reasonable position is somewhere in between: a structurally supported, supply-constrained market for selected metals, wrapped inside the same boom-bust price behaviour commodities have always had. Supercycles are only obvious in hindsight, and the ones that are obvious in advance are usually already priced.
What this means for an Australian investor
A few things worth thinking through before acting on any of it.
You probably own more commodity exposure than you think.
This is the single most important point for an ASX investor. Materials and energy form the second-largest block of the ASX 200 after financials, and the AUD is itself a commodity currency: it strengthens and weakens with the terms of trade. An Australian portfolio built around the index is already a leveraged bet on iron ore, gold and gas. Adding a commodity allocation on top isn’t diversification; it’s concentration wearing a diversification costume. Work out your actual look-through exposure first.
Miners are not the commodity.
BHP set a record $68.77 in late August and fell about 9.5% from it within days while iron ore barely moved. Miners carry operational leverage, cost inflation, capital allocation risk and country risk that the underlying metal doesn’t. They also pay franked dividends, which the metal doesn’t. Choose deliberately which exposure you’re buying.
The access routes differ more than the labels suggest.
Physical or physically-backed gold behaves differently from a broad futures-based commodity ETF, which behaves differently again from producers or royalty companies. Futures-based products carry roll costs that quietly erode returns in the wrong curve environment.
Size it as insurance, not as a view.
Most institutional frameworks land in the mid-single digits for a dedicated commodity sleeve. The discipline that matters isn’t entry, it’s rebalancing: trimming into strength, adding into weakness, and accepting stretches where the position simply drags.
Don’t chase a 14% first half.
The worst time to buy an inflation hedge is after inflation has already shown up in the price. If commodities are a long-term structural allocation, they should be established gradually and held through cycles, not bought in the week the headlines peak.
The uncertainty in this market is real, and it isn’t resolving quickly. But the goal of a hedge is to make your portfolio survivable, not to win the year. Commodities can do the first. Almost nothing reliably does the second.
Signal Savvy Investor provides general information and analytical tools only. Nothing here is personal financial advice, and it does not consider your objectives, financial situation or needs. Commodity investments carry significant volatility and risk of loss. Consider seeking licensed advice before making investment decisions.
